


The recognition and subsequent annual testing of goodwill is one of the most critical and complex areas of financial reporting for multinational companies and large Portuguese entities that have engaged in mergers and acquisitions (M&A). In Portugal, as in the rest of the European Union, companies reporting under International Financial Reporting Standards (IFRS) must strictly adhere to the requirements of IAS 36, Impairment of Assets. This standard mandates that goodwill, an intangible asset representing the future economic benefits arising from other assets acquired in a business combination that are not individually identified and separately recognized, must be tested for impairment at least annually. Given the inherent subjectivity and the high degree of management judgement involved in this process, expert guidance is not just recommended—it is essential for compliance and strategic clarity.
The Mandate of IAS 36 and the Portuguese Context
The core principle of IAS 36 is to ensure that a company’s assets are not carried on the balance sheet at more than their recoverable amount. For goodwill, this involves a specific, non-optional quantitative test at the level of the Cash-Generating Unit (CGU) or a group of CGUs.
A CGU is defined as the smallest identifiable group of assets that generates cash inflows that are largely independent of the cash inflows from other assets or groups of assets. Correctly identifying and delineating CGUs is the foundational step in the impairment process, and it requires a deep understanding of the entity's internal management reporting structure and how the goodwill is monitored. In the dynamic Portuguese business landscape, where subsidiaries or regional operations may be part of a larger European group, correctly allocating the acquired goodwill to the appropriate CGUs is a critical and often contentious step. An incorrect CGU definition can fundamentally flaw the entire impairment analysis, leading to potential audit qualifications and regulatory scrutiny by bodies like the Comissão do Mercado de Valores Mobiliários (CMVM) for listed companies.
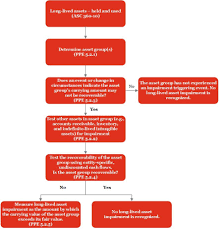
The annual goodwill impairment test under IAS 36 is performed by comparing the carrying amount of the CGU (including the allocated goodwill) with its recoverable amount. The recoverable amount is defined as the higher of:
If the carrying amount exceeds the recoverable amount, an impairment loss is recognized. This loss is first used to reduce the carrying amount of the goodwill allocated to the CGU, and any remaining loss is allocated pro-rata to the other assets of the CGU. This accounting event is significant as it directly impacts a company's financial statements, leading to a non-cash charge against profit and loss, which can influence investor perception and debt covenants. The requirement that an impairment loss for goodwill can never be reversed adds a layer of permanence and critical importance to the initial testing process.
While the accounting standard is international, its application in Portugal faces unique challenges rooted in the local business environment, economic fluctuations, and enforcement practices.
Portugal's economy, while stable, can be sensitive to global and European economic shifts. For the VIU calculation, companies must rely on cash flow projections and a highly subjective discount rate (the Weighted Average Cost of Capital, or WACC). The WACC calculation for a Portuguese CGU involves determining a risk-free rate, a market risk premium, and a country-specific risk premium to appropriately reflect the risks of operating in the market. In periods of economic uncertainty, justifying these long-term forecasts and the discount rate assumption to auditors and regulators becomes exceptionally difficult. Management needs to demonstrate that the assumptions used in the five-year forecasts and the long-term growth rate are prudent, realistic, and consistent with the external market data specific to the Portuguese industry.
Goodwill impairment testing is fundamentally a valuation exercise. Determining the FVLCOD often requires comparison with market transactions involving similar Portuguese or Iberian businesses, which may have limited public data. Calculating the VIU involves complex discounted cash flow (DCF) modeling. Few internal finance departments possess the required combination of advanced valuation skills, deep understanding of IAS 36 nuances (such as the treatment of deferred taxes, non-controlling interests, and specific CGU-level debt), and independence necessary to withstand external audit scrutiny. The lack of proper disclosure and the use of boilerplate language in impairment testing—a frequent criticism by European regulators—highlights the widespread need for expert, entity-specific reports.
Aviaan is positioned as a strategic partner to businesses operating in Portugal, providing comprehensive, independent, and auditor-defensible Goodwill Impairment Services. Our methodology goes beyond mere compliance, offering a strategic view of your business's financial health and performance drivers.
The independence of the valuation specialist is paramount. Aviaan provides a third-party, objective assessment that significantly enhances the credibility of the impairment analysis with auditors and stakeholders. Our services are structured to ensure every aspect of the valuation is robust:
Aviaan works closely with the client’s management team in Portugal to critically assess and document the identification of CGUs. This involves reviewing internal reporting, management's decision-making processes, and cash flow interdependencies to confirm that the CGUs align with the lowest level at which goodwill is monitored. We then provide a sound, defensible rationale for the allocation of goodwill to those CGUs, addressing complex issues like shared corporate assets and multi-territory operations common in Portugal-based regional headquarters.
Compliance with IAS 36 is heavily reliant on the quality of documentation and disclosure. Aviaan’s final deliverable includes a detailed, narrative-rich report that:
This level of detail significantly reduces the risk of audit complications, saves internal finance team time, and provides management with confidence in their reported figures.
A large European holding company, "EuroTech Group," acquired a fast-growing software development firm in Lisbon, Portugal, for a significant premium, resulting in a substantial amount of goodwill. In the subsequent year, a slowdown in the European tech market, combined with rising interest rates in the Eurozone, created indicators of impairment for the Portuguese Cash-Generating Unit (CGU). The internal finance team, while competent, lacked the specialized valuation bandwidth to conduct an independent, annual goodwill impairment test that would satisfy their Big Four auditor.
The core challenge lay in the high subjectivity of the VIU calculation. The Portuguese CGU's projected cash flows were optimistic based on management's prior internal plans, and the general economic downturn made the assumption of aggressive growth difficult to justify. Furthermore, the CGU's WACC needed to be re-evaluated to reflect the current high-inflation and high-interest-rate environment specific to Portugal's capital markets.
Aviaan was engaged to perform the independent goodwill impairment test.
Goodwill impairment testing is a non-negotiable compliance obligation for IFRS-reporting companies in Portugal. The process demands a specialized skill set that merges advanced financial valuation with deep regulatory understanding. The high degree of subjectivity in defining CGUs, forecasting cash flows, and determining the appropriate discount rate necessitates the involvement of independent experts. Aviaan offers unparalleled Goodwill Impairment Services in Portugal, helping businesses to meet their IAS 36 compliance requirements with precision, authority, and strategic foresight. By partnering with Aviaan, you not only ensure an auditor-defensible position but also gain valuable, objective insights into the true economic value and performance of your acquired assets in the Portuguese market.
Related posts
Goodwill Impairment Services in Portugal
Goodwill Impairment Services in Peru
Goodwill Impairment Services in Bangladesh
Goodwill Impairment Services in Greece
Goodwill Impairment Services in Iraq
Goodwill Impairment Services in Qatar
Goodwill Impairment Services in Vietnam
Goodwill Impairment Services in New Zealand
Goodwill Impairment Services in Algeria
Goodwill Impairment Services in Kazakhstan




